Last week, my friend Arjun called me in a mild panic. He’s been waiting to buy his first apartment in Bengaluru since 2023, watching interest rates hover like a stubborn drone that refuses to land.
"Is it ever going to get cheaper?" he asked. I told him to sit tight.
Well, yesterday, the waiting game ended. Sort of.
If you have a loan, or are planning to take one, this weekend brought the best news you’ve heard in years.
After the RBI cut the repo rate to 5.25% earlier this month, SBI finally bit the bullet yesterday and slashed its lending rates by 25 basis points.
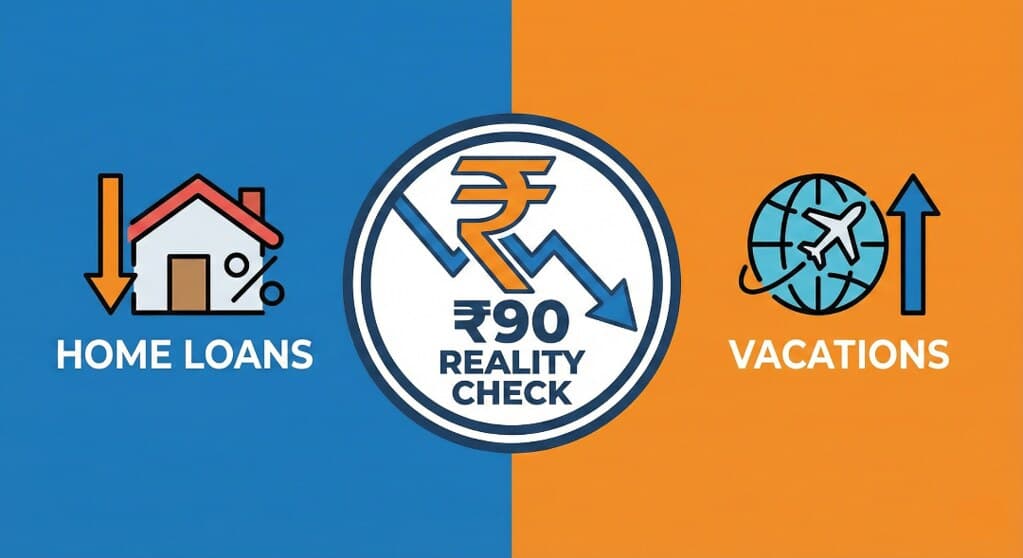
In plain English, the biggest bank in India just made money cheaper. If you are on a floating rate home loan, your EMI is about to shrink.
And SBI rarely moves alone. Other banks usually follow it like lost puppies, so expect HDFC and ICICI to announce similar cuts very soon.
Finance folks love this term because it sounds complicated. It really isn’t. One basis point is just 0.01%. 100 bps equals 1%.
25 bps equals 0.25%. So if your loan rate was 8.50%, a 25 bps cut brings it down to 8.25%. It looks small, but over 20 years, it saves real money.
Here’s where things get uncomfortable.
While domestic borrowing is getting cheaper, India’s global purchasing power is taking a hit.
The Rupee closed at an all time low of ₹90.41 against the US Dollar yesterday.
Why does this matter? Because while your EMI might save you a couple of thousand rupees a month, everything we import is getting more expensive.
From the next i Phone to the fuel in your car, a weaker Rupee quietly pushes prices higher. In simple terms, a weak currency imports inflation.
That puts the RBI in a tough spot. Cut rates to boost growth, which is good. But cutting rates can weaken the currency further, which is bad.
So the big question is sustainability. If the Rupee keeps sliding toward 92 or even 95, the RBI may have to slam the brakes and hike rates again just to defend the currency.
We are not out of the woods yet.
Still confused about how RBI decisions affect your home loan? Think of it like buying apples.
The RBI is the farmer. The bank is the grocery store. You are the customer.
The repo rate is the wholesale price the grocery store pays the farmer for apples. When the farmer drops prices, the store should lower prices for you.
Yesterday, SBI finally changed the price tag.
But here’s the twist. The truck delivering those apples runs on imported petrol. And that fuel just became a lot more expensive.
The cost of one US Dollar at yesterday’s close. Back in 2014, this number was around ₹60. If you were saving for foreign education, your fund just shrank by roughly 33% in a decade.
The bottom line: If you already have a home loan, this is a good time to explore refinancing while rates are low.
But if you are planning that New York vacation, you might want to wait until the currency finds its footing.
Fun fact: In 1947, one US Dollar was roughly equal to one Indian Rupee. We have come a long way since then. Mostly downhill.
If market noise stresses you out, you are not alone. That is exactly why we built First Scroll.
It is a daily, five minute, mobile first finance read explaining what happened, why it matters, and what to remember without hype or panic.
If this article helped you think clearly today, you will enjoy reading First Scroll every morning.
Subscribe to First ScrollSources: The Hindu | Economic Times