In today's FirstScroll, we break down why the regulator is letting companies rewrite their IPO plans at the 11th hour, and why this freedom comes with a new set of watchful eyes.
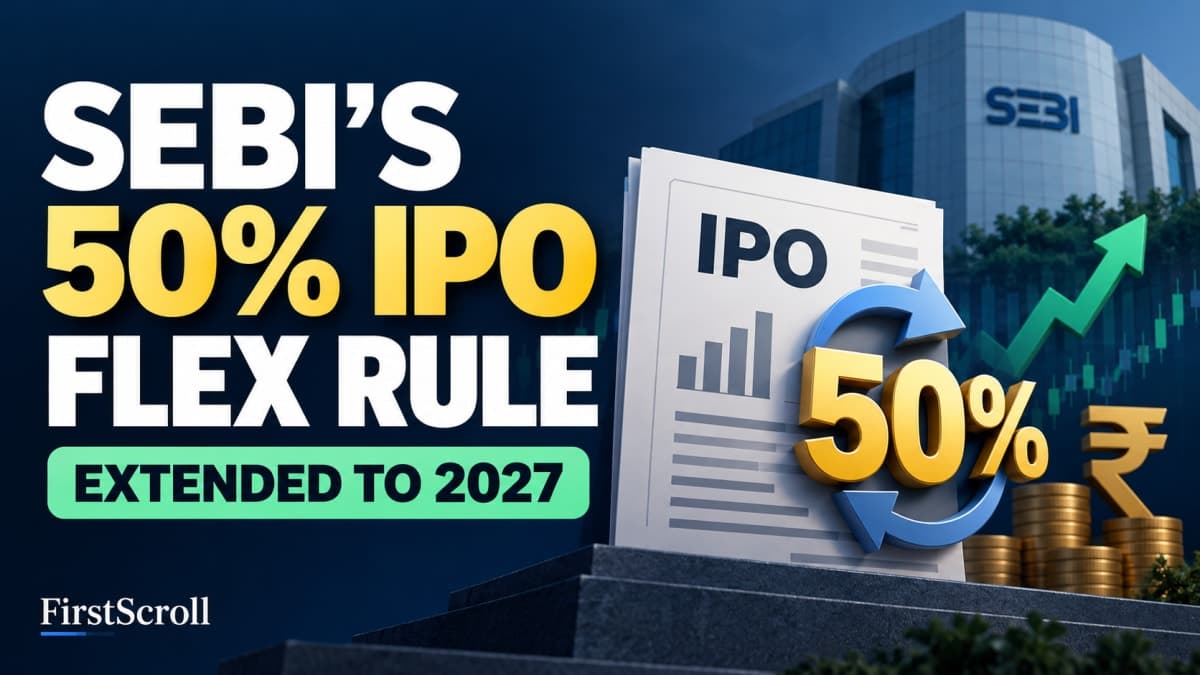
The short answer: SEBI is extending a rule that allows companies to change their fresh fundraising targets by up to 50% without restarting the paperwork, a move aimed at helping firms navigate market swings. To balance this freedom, the regulator has also proposed making third party monitoring mandatory for all public issues to ensure companies do not misuse the cash.
The Story
Imagine you are the founder of a fast-growing Indian tech firm in late 2026. You have spent months preparing for your Initial Public Offering (IPO), filing thousands of pages of documents to raise a specific amount of money for a new factory.
Just as you are about to launch, the market turns volatile. Suddenly, your investors are nervous, or perhaps a rival has just been acquired, making your expansion plans more expensive than you thought. You need to change how much money you are asking for.
Under the old rules, if you wanted to change your fundraising target by more than a small margin, you had to tear up your plans and start the approval process from scratch. It was a procedural nightmare that could take months.
Then, the regulator decided to give companies an escape hatch. On Monday, the Securities and Exchange Board of India (SEBI) communicated to investment bankers that it is extending a special relaxation until March 31, 2027.
This rule lets you slash or hike your fundraising target by a massive amount without hitting the reset button on your regulatory filings. And companies have been using this freedom to the fullest.
And here is the strange part. Even with global uncertainty, India's IPO market is moving at a breakneck pace. In just the July to September quarter, companies raised ₹94,649 crore through public issues.
So here's the question: if companies can change their fundraising targets so drastically at the last minute, how does SEBI ensure they aren't just playing games with the public's money?
You see, the problem is not that companies want more or less money. It is the time it takes to get permission to change those targets.
In a normal market, SEBI rules say that if you change your IPO size by more than 20%, you must file fresh draft documents. Think of it like a wedding budget: if you suddenly decide to invite 50% more guests, the caterer needs a completely new contract, not just a verbal update.
But the market in 2026 is moving faster than the paperwork. The Association of Investment Bankers of India (AIBI) flagged that revising sizes was becoming a major hurdle. So, SEBI pushed the allowable change up to 50% for the fresh issue component of an IPO.
For context, an IPO usually has two parts. First, there is the fresh issue, which is new money coming into the company to fuel growth. Then, there is the Offer for Sale (OFS), where early investors and founders sell their existing shares to cash out.
This 50% flexibility only applies to the fresh issue. It is meant to help companies adjust to "evolving business needs," while the OFS portion remains more strictly controlled to prevent IPO shares crashing due to massive insider exits.
Think of this flexibility as a shock absorber for the stock market. During the recent July to September quarter, 69 mainboard companies raised ₹90,482 crore, while 92 smaller SME firms raised ₹4,167 crore in capital. Without this rule, many of those deals might have stalled in the filing room.
Now, you might wonder why you should care about the paperwork behind the scenes. Because when companies raise thousands of crores from the public, there is always a risk that the money will not be used for the "factory" they promised in the brochure.
So who wants what here? The companies want the freedom to change their mind as the economy shifts. The bankers want to close deals quickly. And the regulator wants to ensure that "flexibility" does not become a cover for poor planning or misuse of funds.
This is where the new monitoring proposal comes in. To balance the extra freedom companies are getting, SEBI now wants to make the appointment of a monitoring agency mandatory for all public issues regardless of size.
Currently, smaller issues often skip this oversight. But the new proposal aims for total transparency and accountability in how every rupee of issue proceeds is utilized. These agencies would act as independent watchdogs, reporting back to stock exchanges on whether the company is sticking to its promises.
But here's the twist. SEBI is not just asking nicely: it is bringing a stick to the party. The regulator has proposed a monetary fine of ₹50,000 for every single instance where a company refuses to cooperate with its monitoring agency.
If a company continues to hide information, the monitoring agency will be empowered to submit a "statement of non-cooperation" directly to the stock exchanges based on whatever information they can find. The exchanges will then display these warnings prominently on their websites for all investors to see.
It gets even tougher. For companies that keep ignoring the rules, SEBI has proposed a graded enforcement system. If the default persists, the exchanges can issue notices to the promoters and eventually freeze promoters' demat accounts through depositories.
This is a significant escalation from the SEBI settlement mechanism often used to resolve minor paperwork errors. By targeting the promoters' own personal shareholdings, the regulator is making it clear that transparency is not optional.
Now to be clear, these monitoring rules are still in the proposal stage. SEBI has asked the public to weigh in with comments until November 3, as it looks to finalize the framework. The extension of the 50% flexibility rule, however, is already in motion to keep the IPO engine running.
The regulator also gave some extra breathing room by extending the validity of IPO observation letters: essentially the "permission to launch" notice: by six months for those that were due to expire earlier this year. It is all part of a larger effort to make the process more efficient while keeping a tighter grip on where the money goes.
So, is SEBI’s latest move about giving companies a free pass? Not really. It is about acknowledging that in a fast-moving economy, fixed targets can become obsolete before the ink is dry on the approval.
India is betting that it can have the most flexible IPO market in the world, as long as it also has the most watchful eyes. Whether that balance of trust and policing can prevent the next big corporate governance lapse is something only time will tell.
Until then…
If this story helped you make sense of why SEBI is changing IPO rules, share it with a friend on WhatsApp, LinkedIn, or X.