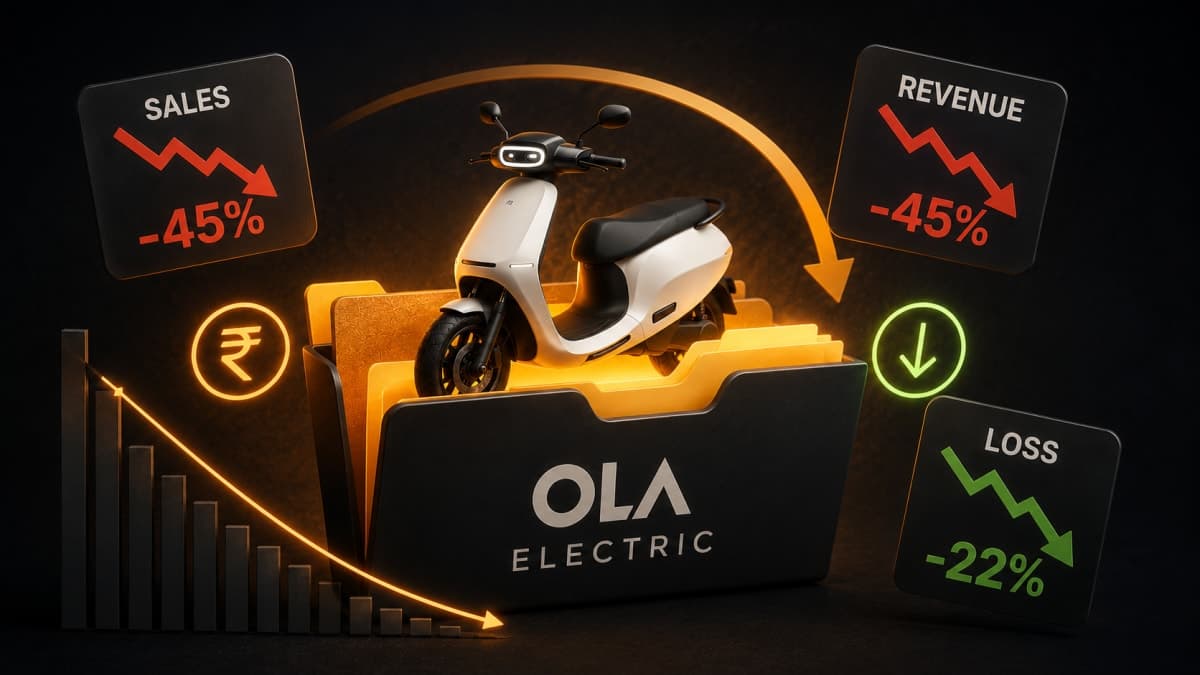
In today's FirstScroll, we break down how Ola Electric sold far fewer scooters, watched its revenue fall by nearly half, and still lost less money than the year before.
With that out of the way, let's dive into today's story.
The Story
For a while, Ola Electric was the loudest story in Indian mobility. The scooters were everywhere, the founder was everywhere, and the market share charts pointed one way: up. It listed on the stock exchange in 2024 to a roaring debut, and for a moment it looked like India had found its electric champion.
Then the momentum turned. Rivals like Bajaj and TVS came for the same buyers, service complaints piled up, and the sales that once only grew began to shrink. What followed was a year the company itself now calls a reset.
Which brings us to the numbers that came out this month, and the strange shape of them.
In the June quarter, Ola Electric's revenue fell 45% from a year earlier, from ₹828 crore down to ₹455 crore. It delivered 39,192 scooters against 68,192 the year before. By almost any measure, the business got smaller.
And yet, over the same stretch, its net loss got smaller too, narrowing to ₹336 crore from ₹426 crore.
So the question is, how does a company sell fewer scooters, earn far less money, and still bleed less than it did before?
To see it, you have to look at the two halves of a loss separately.
You see, a loss is just revenue minus costs. When revenue falls, the loss usually widens, unless costs fall even faster. And that is exactly what happened here. Ola cut its total expenses by nearly 42%, from ₹1,065 crore to ₹620 crore. Revenue dropped 45%, costs dropped 42%, and because the company was starting from a base where it spent far more than it earned, shrinking the spending moved the loss more than shrinking the sales did.
Look at where the axe fell. Employee costs dropped 46% to ₹48 crore. Manufacturing and material spending came down hard. This is the arithmetic of a reset: a company deciding it had built a cost structure for a scale it never reached, and cutting back to fit the size it actually is.
So the smaller loss is not a story about selling more. It is a story about spending less. And there is a real improvement underneath it. The company's gross margin, the money left after the direct cost of making each scooter, rose to 30.5% from 25.8% a year earlier. Ola is keeping more from every rupee of sale than it used to, partly because it now makes more of its own battery cells rather than buying them.
But here's the twist, and this is where you strip the makeup off the number. Part of that narrower loss was not operational at all. The results included a one-time provision reversal of about ₹57 crore, an accounting entry that flattered the reported loss this quarter and will not repeat next quarter. Take it out, and the underlying loss is a little worse than the headline suggests. The improvement is real, but it is wearing a touch of makeup.
There is a second thing the year-on-year comparison hides. Compared to the previous quarter, not the previous year, Ola actually grew. Revenue jumped 72% from ₹265 crore, deliveries nearly doubled, and market share climbed back from 5.1% to 8.4%. The company's framing is that the quarter a year ago was still healthy, while the quarter just before this one was the rock bottom of the reset. Measured from the bottom, this looks like a recovery. Measured from a year ago, it looks like a decline. Both are true, and which one you lead with is a choice.
Now, why should you care which comparison is honest? Because a recovering business and a shrinking business get valued very differently, and Ola is asking the market to believe in the first while the year-on-year numbers still show the second. One good quarter measured against the worst one does not settle that. Two or three would.
There is also the small matter of cash. Even a narrower loss is still a loss, and the company raised ₹780 crore through a share sale in June to keep the balance sheet strong. A leaner cost base buys time. It does not, on its own, prove the demand will come back.
So the headline paradox dissolves once you separate the two halves. Ola did sell less and earn less. It simply cut its spending faster than its sales fell, and a one-off entry helped the optics along. The real question the numbers cannot yet answer is whether the leaner, cheaper Ola can now start growing sales again, or whether it has only learned to lose money more slowly.
Whether this reset becomes a turnaround is something the next few quarters, not this one, will decide.
Until then…
If this helped you read past the headline on a results day, share it with a friend on WhatsApp, LinkedIn or X. You might also enjoy our guide to how to read a drhp.